


Key Highlights
- Continental equities experienced modest Friday declines but secured their first positive weekly performance in three weeks
- The Federal Reserve implemented a 25 basis point rate increase to 3.75%-4%, marking its initial hike since mid-2023, calming investor sentiment
- Brent crude oil maintained levels around $104 per barrel following a midweek surge past $113 triggered by infrastructure attacks
- The Bank of England maintained its 3.75% rate but signaled potential tightening in November
- Technology shares led gains while energy, telecommunications, and luxury sectors underperformed on Friday’s session
European stocks experienced modest declines on Friday’s trading session but maintained positive territory for the week following volatile market conditions sparked by energy supply concerns and monetary policy announcements.
The Stoxx Europe 600 index retreated approximately 0.44% during Friday’s session, stepping back from the previous day’s peak that marked its highest level in over a week. Germany’s benchmark DAX and France’s CAC 40 both declined roughly 0.7%, while Britain’s FTSE 100 shed 0.6%.
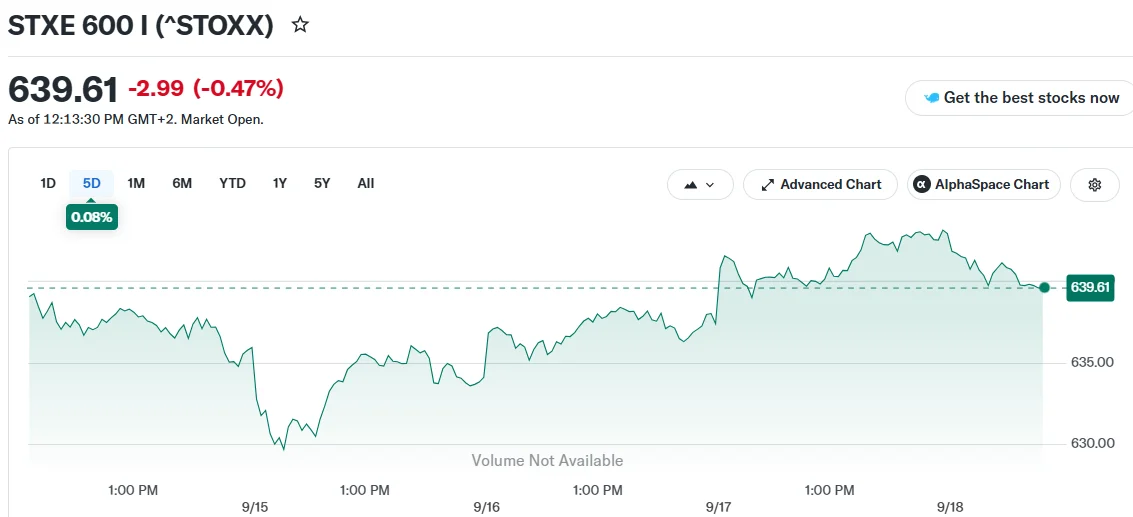
Notwithstanding Friday’s retreat, the Stoxx 600 was positioned to finish the week with approximately 0.5% gains. This would represent its initial weekly advance in three weeks.
Federal Reserve’s Rate Decision Provides Market Stability
The Federal Reserve delivered a unanimous decision to increase interest rates by 25 basis points, establishing a new range of 3.75% to 4%. This marked the central bank’s initial rate elevation since the middle of 2023.
Fed Chair Kevin Warsh emphasized the central bank’s commitment to combating inflation, regardless of external political pressures. This resolute stance helped stabilize investor confidence and fueled Thursday’s strongest single-day rally for the Stoxx 600 in more than two months.

The Bank of England maintained its benchmark rate at 3.75% in a split 6-3 decision. Policymakers cautioned that continuing energy cost inflation could necessitate an increase to 4.00% during their November policy meeting.
The Bank of Japan elevated rates to a three-decade high, although two board members dissented, creating uncertainty about the sustainability of its monetary tightening trajectory.
Crude Prices Remain Elevated Following Infrastructure Incident
Brent crude retreated approximately 1.5% during Friday trading but remained nearly 15% higher for the week, stabilizing close to $104 per barrel.
Earlier during the week, a deliberate assault on Saudi Arabia’s East-West pipeline infrastructure created concerns affecting up to 4% of worldwide oil supplies. Additional Houthi attacks in the Red Sea region propelled Brent beyond $113 per barrel and drove the US 10-year Treasury yield above 5% for the first time since 2007.
By Friday’s session, energy corporations and shipping companies had established alternative routing through Oman, contributing to reduced pricing pressures.
Nestle shares declined between 1% and 1.3% following Russia’s seizure of the Swiss food manufacturer’s in-country operations.
Orange plummeted nearly 4%, positioning it as the Stoxx 600’s poorest performer. Shell retreated 1.2% while Allianz declined 1.3%.
Conversely, ASML Holding advanced 2.1% and STMicroelectronics climbed 2.2%, with technology stocks ranking among the week’s strongest performers.
Polish fashion merchant LPP surged 6% following disclosure of a 64% second-quarter profit increase.
Interest rate-sensitive industries including luxury goods edged lower as elevated bond yields continued pressuring valuations.
The week concluded with European markets rebounding from Tuesday’s pronounced selloff, when the Stoxx 600 reached its lowest point since June.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


