


Key Highlights
- Major European indices plunged to their lowest levels in several months during Tuesday’s session
- Brent crude oil climbed beyond $113 per barrel following strikes on Saudi Arabian pipeline systems
- Financial markets indicate a 90% probability of a 25 basis point Federal Reserve rate increase on Wednesday
- Senior executives from OpenAI and Anthropic jointly urged a temporary halt to cutting-edge AI system development
- Trustpilot shares plummeted over 18% following a net loss report for the first half of 2026
European equity markets experienced significant declines on Tuesday, with benchmark indices retreating to levels not seen in several months. Investors grappled with mounting geopolitical tensions, escalating energy prices, and anticipation surrounding an imminent Federal Reserve interest rate decision.
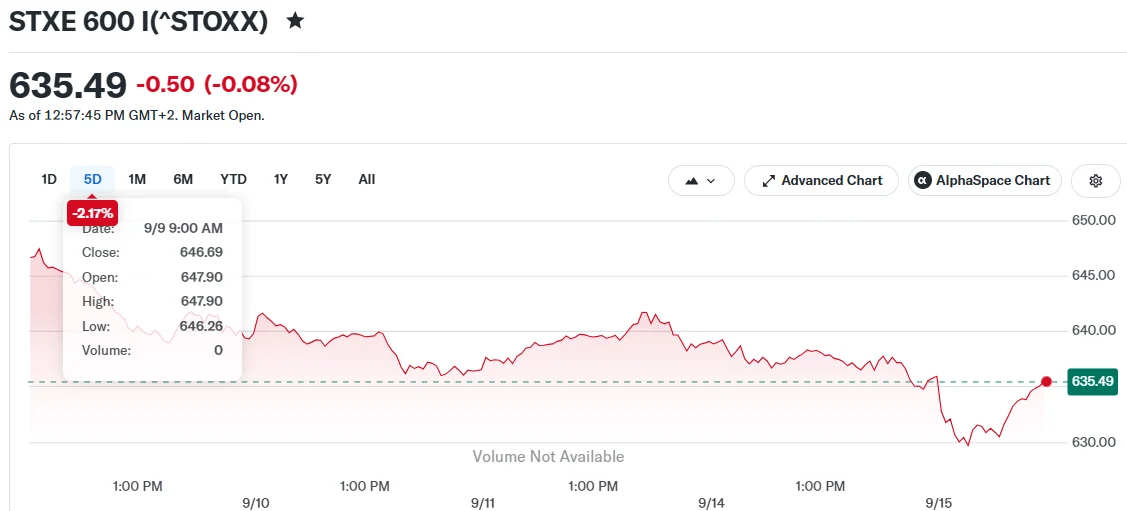
The continent-wide STOXX 600 index declined 0.35%, reaching its weakest position in more than three months. France’s CAC 40 retreated 0.4% to touch a near four-month nadir, while Britain’s FTSE 100 and Germany’s DAX similarly posted losses.
Energy Markets Rally Following Saudi Infrastructure Strike
Surging energy prices represented a primary headwind for European trading floors. Brent crude advanced 1.2% to exceed $113 per barrel, extending a sustained upward trajectory spanning multiple weeks.
Saudi Arabian authorities attributed responsibility to Iranian-aligned factions operating from Iraq for an assault on the kingdom’s East-West petroleum pipeline infrastructure. Government representatives cautioned that the incident could impact as much as 4% of worldwide oil distribution.
Meanwhile, Yemen’s Houthi forces executed additional attacks targeting Saudi territory and commercial vessels navigating Red Sea corridors on Monday. Diplomatic negotiations scheduled in Oman aimed at regional reconciliation were suddenly canceled, diminishing prospects for near-term stability.

The preceding trading day similarly witnessed downward momentum in European markets. Monday’s session saw the CAC 40 decline 0.76% while the DAX shed 0.30%, partially attributed to Arctic region tensions following statements from twelve European Union member states advocating enhanced European strategic positioning there amid Russian concerns.
Federal Reserve Policy Decision Creates Market Uncertainty
The Federal Reserve commenced its two-day monetary policy deliberations on Tuesday, with financial markets assigning a 90% likelihood to a quarter-point rate elevation on Wednesday. The adjustment would mark the Fed’s initial rate increase since the middle of 2023.
The European Central Bank implemented a 25 basis point increase to 2.50% during the previous week. These consecutive monetary tightening actions by leading central banking institutions have sustained elevated borrowing costs.
The benchmark 10-year U.S. Treasury yield remained positioned near 4.98%, approaching territory last witnessed in 2007. Germany’s equivalent 10-year Bund yield maintained proximity to 3.51%.
Market strategists emphasized that the more critical consideration extends beyond whether the Fed implements a hike, but rather the forward guidance Chair Jerome Powell provides regarding subsequent policy trajectories. An elevated U.S. inflation report released last Friday intensified speculation that additional restrictive measures may be forthcoming.
Technology sector equities throughout Frankfurt and Amsterdam faced selling pressure following a joint statement from leadership at OpenAI and Anthropic advocating a provisional deceleration in sophisticated AI system advancement. The appeal referenced the necessity for internationally coordinated risk-assessment frameworks.
ASML shares experienced modest recovery, climbing 1.6%, while BE Semiconductor advanced approximately 1.2% after steeper declines during the previous session.
Trustpilot shares collapsed more than 18% after reporting negative net earnings for the initial half of 2026. The platform’s results suffered from a $6 million regulatory penalty related to competition law violations and American taxation adjustments.
Puig Brands declined 3.5% following disclosure of a €1.2 billion transaction to acquire the outstanding 50% ownership position in dermatological brand ISDIN.
Investment professionals now await Wednesday’s Federal Reserve announcement for the subsequent pivotal indicator of market trajectory.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


