


Key Highlights
- The greenback reached its strongest position in more than seven days during Tuesday’s trading session
- Traders are pricing in a 92.1% probability that the Federal Reserve will raise rates at Wednesday’s meeting
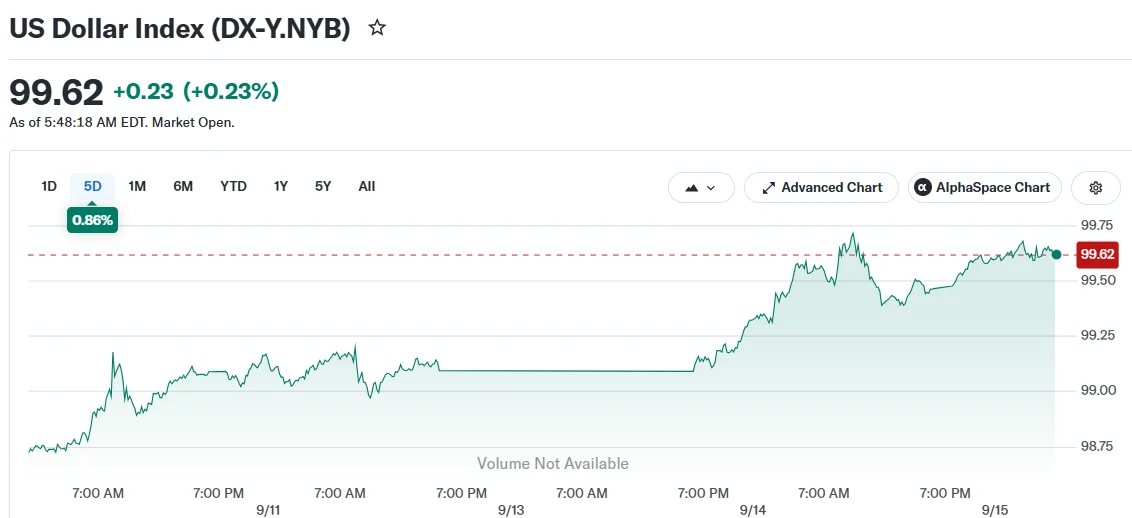
- The Dollar Index advanced approximately 0.24% to trade around the 99.60 level
- Brent crude oil prices jumped above $113 per barrel following infrastructure attacks in Saudi Arabia
- The euro declined to month-low levels around $1.1539, while Japan’s yen weakened to seven-day lows
The U.S. dollar advanced during Tuesday’s session, reaching its most robust level in over seven days as market participants dramatically raised their expectations for a Federal Reserve interest rate increase at the upcoming policy gathering this week.
The Dollar Index, a gauge measuring the American currency against a basket of six major rivals, climbed approximately 0.24% to hover around 99.60. The previous session saw the index touch a one-month peak at 99.736.
Financial markets are now viewing a Fed rate adjustment as virtually guaranteed. According to CME FedWatch data, the likelihood of a 25-basis-point increase into the 3.75%-4.00% target range stands at 92.1%, a substantial jump from approximately 60% recorded just one week earlier. Additionally, money markets are factoring in a 53.4% probability of another rate adjustment at the October policy meeting.
Crude Oil Rally Amplifies Dollar Strength
Crude oil prices provided additional momentum to the dollar’s upward trajectory. Brent crude surged beyond $113 per barrel following new attacks targeting Saudi Arabian pipeline infrastructure and Houthi militant strikes in the Red Sea region.
Elevated oil prices are intensifying inflation worries, which consequently drives Treasury yields upward. The benchmark U.S. 10-year Treasury yield crossed above the 5% threshold on Tuesday, marking the first instance since 2007.

Given that the United States functions as an oil exporter, rising energy costs typically strengthen the dollar. BNY’s John Velis noted that monetary policy must maintain control over inflationary expectations, despite not being ideally positioned to counteract supply-driven shocks.
Analysts at DBS cautioned investors against pursuing the dollar’s rally ahead of the Fed’s policy announcement, pointing out that two senior Federal Reserve officials had expressed openness to maintaining current rates before their communications blackout period began.
European and Japanese Currencies Face Headwinds
The euro retreated 0.1% during the session to trade near $1.1539, representing its weakest position in approximately one month. Market participants are evaluating stagflation concerns within the eurozone against a strengthening dollar, despite the European Central Bank’s recent quarter-point rate increase to 2.50% last week.
The Japanese yen declined 0.3% to reach an over one-week low at 154.82 versus the dollar. This represents a reversal from the seven-month high of 152.89 achieved during the previous week.
The Bank of Japan is scheduled to announce its own rate decision on Friday. Market observers are monitoring whether the BOJ will indicate an accelerated tightening timeline following an anticipated hike to 1.25%.
The yen has appreciated roughly 4% during the current month, propelled by capital repatriation flows and a spike in Japan’s 10-year government bond yield to a 30-year peak of 3.025%.
The current week features multiple significant central bank announcements, with the Federal Reserve’s two-day policy gathering commencing Tuesday and the Bank of Japan’s meeting scheduled for Friday.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


