


Quick Summary
- The Dow Jones jumped 479 points on Friday, posting a 0.9% gain, with the S&P 500 and Nasdaq both advancing 0.5%
- Major equity benchmarks closed the week in positive territory following mid-week pressure
- The benchmark 10-year Treasury yield climbed to multi-decade highs before moderating on Friday
- Crude oil declined amid speculation about potential Strait of Hormuz reopening negotiations
- Market pricing indicates over 60% probability of Federal Reserve rate increase in October
U.S. stocks finished Friday’s session in positive territory, concluding a turbulent trading week. The advance occurred despite Treasury yields climbing to heights not witnessed in nearly two decades.
The Dow Jones Industrial Average added 479 points, representing a 0.9% increase, to settle at 51,829. Both the S&P 500 and Nasdaq Composite registered approximately 0.5% gains.
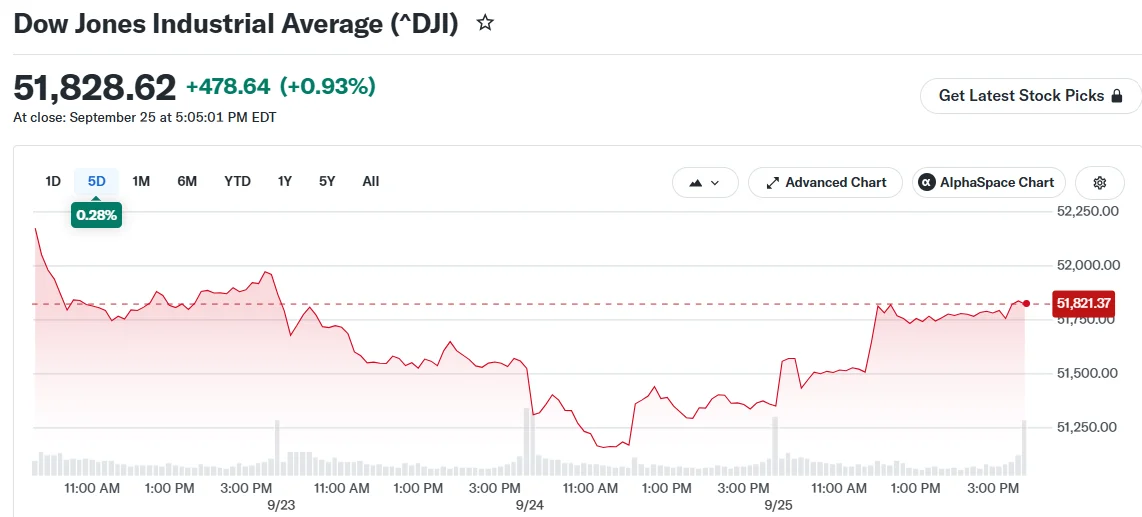
Looking at the full week’s performance, the Dow posted a 0.3% increase. The S&P 500 advanced 1.2%, while the Nasdaq climbed 2%, recovering from losses earlier in the week.
Among individual movers, Akamai Technologies stood out on Friday. The stock appreciated 3% following news of a long-term partnership agreement with Anthropic.
Meta Platforms delivered impressive weekly performance. Shares surged nearly 13% as investors responded enthusiastically to the company’s newly unveiled AI agent technology, Muse.

Treasury Market Turbulence Creates Market Headwinds
Fixed income markets experienced significant volatility throughout the week. The benchmark 10-year Treasury yield climbed to its loftiest level since 2007, briefly touching 5.228% before retreating.
By Friday’s close, it stood at 5.18%, marking a new 19-year peak. The 30-year yield finished at 5.5%, having crossed that threshold for the first time in over two decades.
The two-year yield moved marginally lower, finishing the session at 4.862%.
Multiple catalysts have propelled yields higher. Contributors include aggressive rhetoric from Federal Reserve policymakers, elevated energy costs stemming from Middle Eastern tensions, and purchasing managers data that exceeded forecasts.
Fed funds futures markets currently reflect approximately 64% to 66% odds of a rate increase next month. Market participants are anticipating three additional quarter-point increases through late 2027.
Crude Prices Retreat on Diplomatic Progress Speculation
Oil prices declined throughout the week following reports suggesting U.S. and Iranian officials were engaged in discussions regarding potential reopening of the Strait of Hormuz. Iran has purportedly requested the U.S. recommit to a June memorandum of understanding.
West Texas Intermediate crude decreased 2.33% to close at $92.41 per barrel. Brent crude, the global pricing benchmark, declined 2.14% to finish at $104.32 per barrel.
Market participants also monitored U.S.-China relations this week. Trade discussions proceeded during Chinese President Xi Jinping’s diplomatic visit to American soil.
Treasury Secretary Scott Bessent indicated both nations agreed to a two-month extension of their existing trade truce. Additional information regarding the negotiations is anticipated in coming days.
Consumer sentiment figures were also released Friday. The University of Michigan’s September index declined but exceeded initial projections.
The report indicated consumers’ inflation expectations increased across timeframes, including long-term projections. This development provides another consideration for Federal Reserve policymakers as they approach upcoming decisions.
Market observers note that persistently elevated yields may ultimately pressure equity valuations and economic expansion. However, others highlight the economy’s durability thus far despite headwinds.
Market participants will remain focused on bond market movements, energy prices, and trade negotiation progress for signals about future direction.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


