


TLDR
- Micron shares dropped roughly 2% Thursday morning to $1,046.37 during premarket hours, despite surging nearly 600% in the last year.
- UBS’s Timothy Arcuri maintained his Buy recommendation and increased his price target to $1,625, pointing to growing supply-demand imbalances in memory chips.
- Citi’s Atif Malik similarly upheld his Buy stance and boosted his target from $1,150 to $1,300, driven by robust DRAM pricing trends.
- Share repurchase limitations linked to Micron’s 2024 Chips Act grant will end on Dec. 9.
- The company is scheduled to announce fiscal Q4 results on Sept. 30, with investors eager to see if pricing momentum translates to the bottom line.
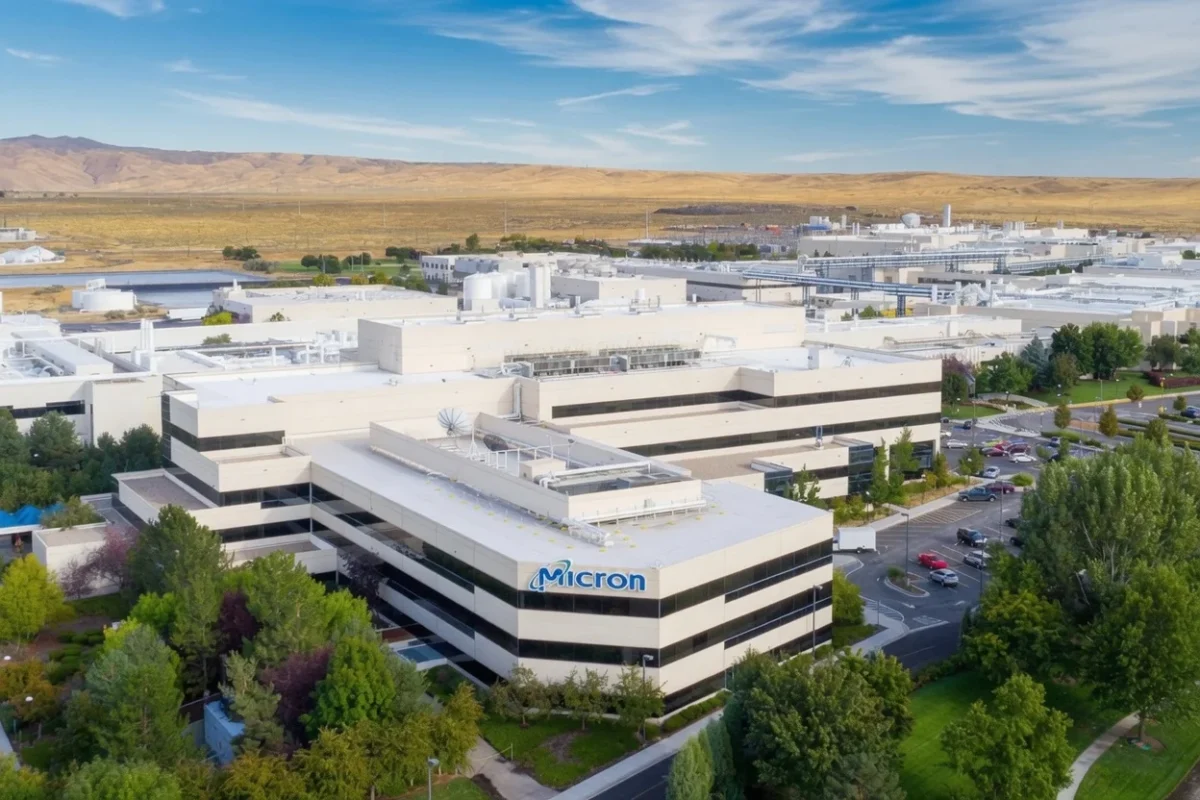
Micron Technology shares declined approximately 2% Thursday, hovering around $1,046 during early trading hours. The modest retreat follows an extraordinary 12-month rally that delivered gains approaching 600%.
Despite the morning slide, two prominent Wall Street firms continue to see substantial upside potential. Analysts from UBS and Citi reaffirmed their bullish positions this week, emphasizing persistent supply constraints in the memory semiconductor market.
UBS’s Arcuri took an aggressive stance with his updated forecast. His $1,625 price objective reflects an eight-times forward price-to-earnings ratio applied to his 2029 earnings projections for the memory giant.
The Bull Case for Continued Growth
The optimistic outlook hinges on fundamental supply-demand dynamics. Artificial intelligence infrastructure requires massive memory capacity, and semiconductor manufacturers are struggling to meet the demand.

Arcuri’s recent industry research indicates an expanding mismatch between customer requirements and available supply. He anticipates Micron will deliver fiscal Q4 revenue of $52.4 billion when it reports on Sept. 30, alongside earnings per share of $32.50.
Malik from Citi projects similar figures. His estimates call for fourth-quarter revenue of $51 billion and EPS of $31.45, both slightly exceeding Wall Street consensus estimates.
His forward projections extend into fiscal Q1 2027, where he anticipates revenue reaching $57 billion with EPS climbing to $35.25.
Market pricing dynamics support the bullish narrative. Citi now projects blended DRAM prices will increase 20% quarter-over-quarter in fiscal Q4, followed by an additional 13% gain in the subsequent quarter.
Malik believes supply constraints will persist across both DRAM and NAND segments, though he anticipates price appreciation will moderate over the coming year. His analysis suggests pricing will peak during Q2 2027.
Share Repurchase Program on the Horizon
An often-overlooked catalyst involves Micron’s capital allocation flexibility. The company currently faces restrictions on large-scale buybacks and special dividends due to conditions tied to its 2024 Chips Act funding package.
These limitations sunset on Dec. 9. Arcuri projects Micron could launch buyback programs starting around $20 billion quarterly, potentially expanding to $50 billion per quarter by fiscal 2027’s conclusion.
This combination of pricing strength and capital returns underpins Arcuri’s conviction even in bear-case scenarios. His analysis suggests that even if spot market memory prices collapsed 80% when the AI-driven cycle eventually moderates—which he forecasts for late 2028—Micron would still generate higher annualized earnings than current levels.
Long-term supply contracts and the anticipated share repurchase initiative form the foundation of this projection.
Citi is monitoring Micron’s capital allocation strategy carefully. The firm projects approximately $50 billion in capital expenditures for fiscal 2027, with equipment purchases exceeding $20 billion of that total.
Micron’s market capitalization has surpassed $1 trillion following this year’s extraordinary performance. The critical near-term catalyst arrives with the Sept. 30 fiscal Q4 earnings release, which will reveal whether robust pricing trends are materializing in financial results matching analyst expectations.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


