


Quick Summary
- U.S. equity futures declined Thursday morning with Dow, S&P 500, and Nasdaq all pointing lower as Treasury yields surged to levels unseen in nearly two decades.
- The benchmark 10-year Treasury yield climbed to 5.14%, marking its highest point since July 2007, while the 30-year yield touched 5.44%, a level last seen in 2004.
- Market expectations for a Federal Reserve interest rate increase next month jumped to 71%, a significant rise from the previous day’s 55% probability.
- A Washington summit between President Trump and Chinese President Xi Jinping resulted in an extension of the bilateral trade truce through January 10.
- Darden Restaurants saw shares decline following disappointing quarterly results, with market participants awaiting Costco’s earnings release after Thursday’s closing bell.
US stock futures traded lower Thursday morning as market participants balanced concerns over climbing bond yields with optimism surrounding potential breakthroughs in trade negotiations and Middle Eastern diplomatic efforts. The downturn extended Wednesday’s losses and suggested investors would approach Thursday’s session with caution.
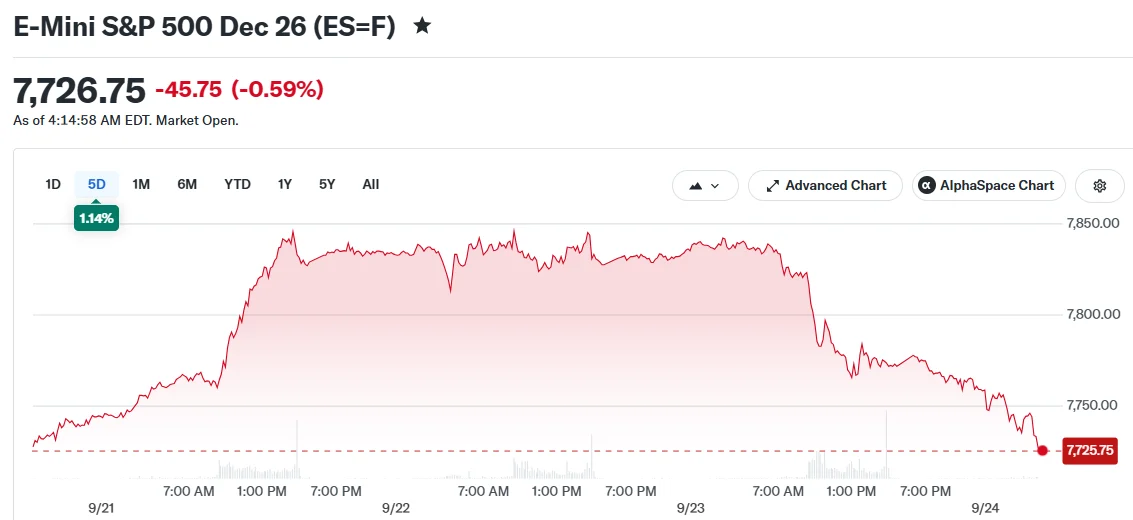
Dow Jones Industrial Average futures retreated between 0.3% and 0.5% across various readings, with S&P 500 futures sliding 0.6% to 0.7%. Technology-heavy Nasdaq 100 futures led the decline, falling more than 1%.
Treasury Yields Surge to Levels Not Seen in Nearly Two Decades
The primary catalyst behind Thursday’s negative market sentiment was a significant bond market sell-off. The benchmark 10-year Treasury note’s yield advanced to 5.14%, representing its most elevated reading since July 2007.
Meanwhile, the 30-year Treasury yield pushed as high as 5.44%, marking territory last visited in 2004. Higher yields typically translate to increased borrowing costs for both corporations and individual consumers.
The bond market retreat came on the heels of economic indicators revealing business activity growth that exceeded analyst projections. These robust figures intensified worries that inflationary pressures might persist longer than previously anticipated.

The stronger-than-expected economic data also provided the Federal Reserve with additional justification to contemplate an interest rate increase. Data from the CME FedWatch tool indicated traders now assign a 71% probability to a rate hike at next month’s policy meeting.
This represents a substantial increase from the 55% probability calculated just one day earlier. The rapid shift illustrates how dramatically market sentiment can pivot in response to fresh economic releases.
Not all market observers view the yield surge with alarm. Glen Smith, serving as chief investment officer at GDS Wealth Management, emphasized that financial markets have successfully navigated comparable yield environments in the past.
Smith referenced equity market resilience when yields approached 5% during 2023. He expressed confidence that current corporate earnings momentum could prove sufficient to counterbalance rate-related concerns.
High-Stakes Presidential Summit in Washington
Beyond fixed income market developments, the Washington meeting between President Trump and Chinese President Xi Jinping commanded significant investor attention. Treasury Secretary Scott Bessent announced that both nations agreed to prolong their existing trade truce by an additional two months.
The revised expiration date for the trade agreement is now January 10. Outstanding issues requiring further negotiation encompass artificial intelligence rivalry, the conflict involving Iran, and access to critical mineral resources.
A delegation of prominent American technology company executives was scheduled to participate in a Thursday evening dinner with both heads of state. This business component added another layer of significance to the high-profile diplomatic engagement.
On the corporate front, Meta unveiled cameraless virtual reality glasses at its Connect conference Wednesday evening. The social media giant also announced intentions to begin generating revenue from its Muse AI agent, which has achieved top-ranking status in application marketplaces.
Darden Restaurants experienced share price declines after delivering first quarter financial results that fell short of analyst estimates. Costco Wholesale Corporation was preparing to release its quarterly earnings report following Thursday’s market close.
Market participants were also monitoring upcoming economic releases. Weekly initial jobless claims data and new home sales statistics were scheduled for release during Thursday’s session, both possessing potential to further reshape interest rate expectations.
According to the most recent premarket quotations, the E-Mini Dow stood at $51,692, representing a 0.35% decline. The E-Mini S&P 500 changed hands at $7,725, down 0.61%, while the E-Mini Nasdaq 100 retreated to $30,434.75, reflecting a 1.07% loss.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


