


TLDR
- The STOXX 600 advanced 0.7% on Wednesday, breaking a two-session lull in European equity markets.
- Both Germany’s DAX and the UK’s FTSE 100 posted 0.7% increases throughout the trading day.
- Technology and chip equipment shares surged following President Trump’s endorsement of voluntary artificial intelligence safety protocols.
- Presidential support for accelerated data center construction calmed fears of potential technology sector investment reductions.
- September remains negative for the STOXX 600, tracking toward a 2% monthly decline—the first such drop in half a year.
European stock markets posted solid gains on Wednesday as traders positioned for a wave of key economic data from the eurozone and across the Atlantic.
The benchmark STOXX 600 index advanced 0.7%, breaking free from two consecutive sessions of stagnant trading activity.
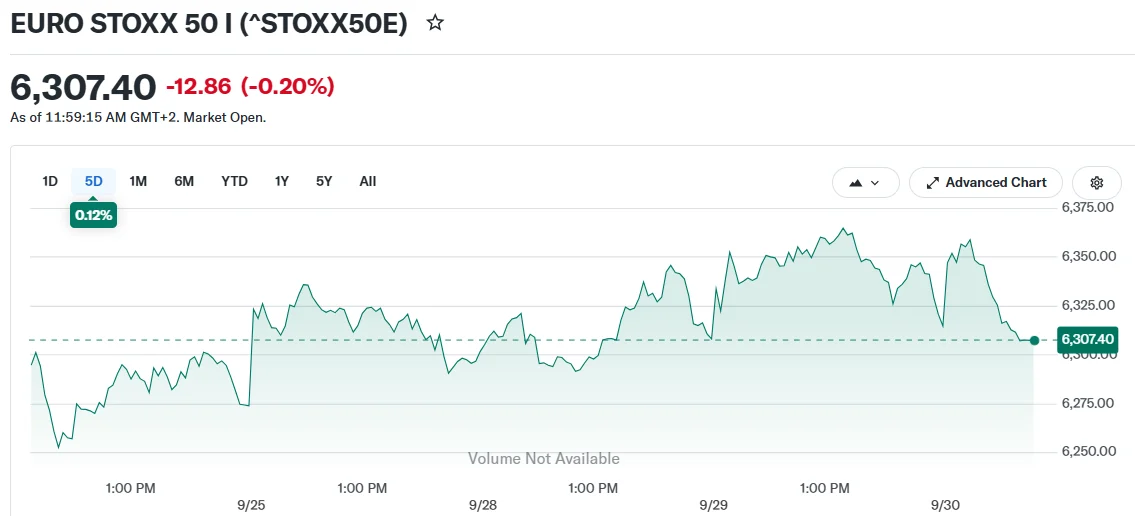
Both Germany’s DAX and the UK’s FTSE 100 registered 0.7% increases during the session. Meanwhile, the STOXX 50 climbed 0.5%, touching its highest level in three weeks.
Technology Sector Spearheads Market Gains
Technology stocks and semiconductor equipment manufacturers posted the strongest performance. The rally followed President Donald Trump’s announcement that major technology companies had committed to voluntary safety frameworks for artificial intelligence development.
The president also reaffirmed his commitment to expediting data center construction across the nation. This statement calmed investor anxieties about potential spending pullbacks following recent reports of AI model training halts at OpenAI.

Companies providing hardware components and energy infrastructure saw the most significant benefits from these announcements. Market participants had expressed concern that regulatory constraints could hinder data center expansion, but the president’s remarks allayed those fears.
ASML shares climbed 0.8% on the day. Novartis advanced 1.1%, while aerospace companies Airbus and Safran posted gains of 1.3% and 1.2% respectively.
However, not all sectors participated in the rally. TotalEnergies dropped 1% as energy stocks slipped into negative territory.
Market Attention Shifts to Key Inflation Releases
Outside the technology space, market participants are preparing for a comprehensive schedule of economic releases. The lineup includes August retail sales data from Germany and employment statistics from Europe’s largest economy.
French consumer price data and September inflation figures from Germany are also scheduled for release. These reports will provide crucial insights into price dynamics throughout the eurozone.
Across the Atlantic, focus centers on the August Personal Consumption Expenditures price index—the Federal Reserve’s favored inflation gauge.
Market analysts anticipate the index will reveal stable price pressures compared to the prior month. A flat reading would provide relief to interest rate-sensitive equity sectors.
Yields on U.S. government bonds have been hovering near levels not seen in decades. A stable inflation print could reinforce expectations that the Federal Reserve has finished its rate-hiking campaign.
Market watchers are also awaiting remarks from European Central Bank policymaker Frank Elderson scheduled for later in the day. His comments could shed light on the economic growth trajectory for the currency bloc.
Monthly Performance Shows First Decline in Six Months
While Wednesday brought positive momentum, September has proven challenging for European equities on the whole. The STOXX 600 is positioned to finish the month approximately 2% lower.
This would represent the index’s first negative monthly performance in half a year, ending a sustained period of summer gains for regional markets.
Multiple headwinds pressured equities throughout the month, including elevated sovereign bond yields, increased energy expenses, and continued uncertainty surrounding artificial intelligence sector dynamics.
Energy commodity prices have risen again this month, partly attributed to stalled diplomatic discussions between Washington and Tehran, intensifying inflation concerns.
Examining the broader third quarter picture, the STOXX 50 remains essentially flat. The STOXX 600 has declined 0.6% over the same three-month span.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


