


TLDR
- European equities advanced approximately 1% during Tuesday’s session, with healthcare names driving the upside.
- Genmab shares surged more than 8% following encouraging late-stage clinical data for a lymphoma therapy developed alongside AbbVie.
- Borrowing costs across the euro zone declined after a recent spike driven by French budget concerns.
- The common currency hovered near a 17-month trough as France’s fiscal challenges and Spain’s sudden election call dampened investor confidence.
- Technoprobe shares rallied after receiving favorable analyst coverage from J.P. Morgan with an “overweight” recommendation.
European stock markets posted solid advances on Tuesday, rebounding from a challenging start to the final quarter for international portfolios.
The pan-European STOXX 600 benchmark climbed nearly 1%. Germany’s DAX index advanced roughly 0.9%, while France’s CAC 40 recovered 0.7% following Monday’s decline.
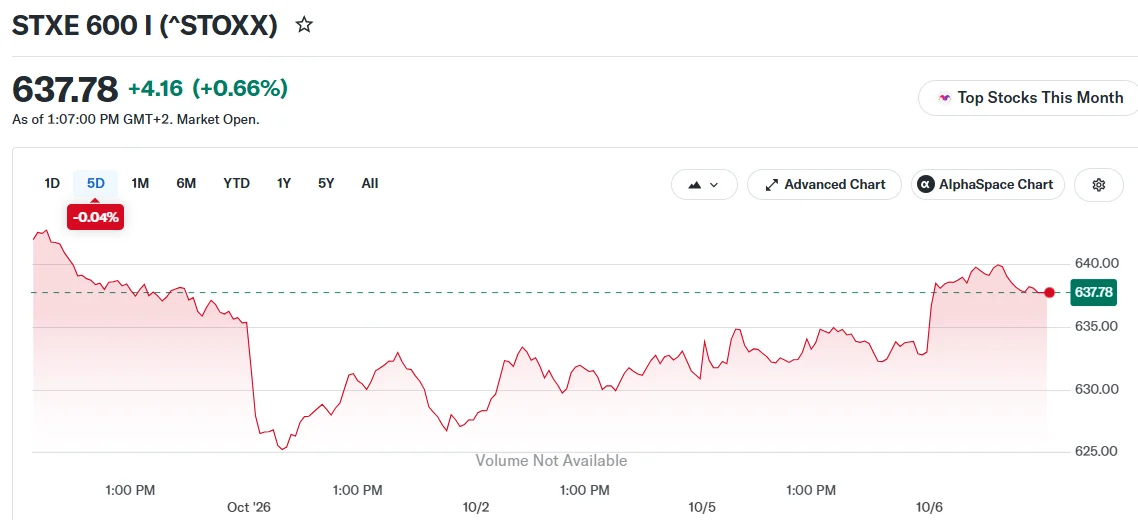
Spain’s IBEX 35 posted a 1.2% gain despite market participants digesting Prime Minister Pedro Sanchez’s announcement of an unscheduled national vote.
The healthcare segment paced the upward movement. The sector gauge increased 1.4%, marking the best performance across all European industry groups.
Genmab Leads Healthcare Gains
Danish biotechnology company Genmab surged over 8%, reaching its highest level in three years. The rally followed positive late-phase trial data showing its collaborative therapy with AbbVie demonstrated efficacy in lymphoma patients.

Trial results indicated the combination therapy lowered the risk of disease advancement or mortality in newly diagnosed individuals. Market observers viewed the findings as encouraging for both pharmaceutical partners.
Italian pharmaceutical company Recordati also posted gains after private equity investor CVC increased its acquisition bid to 53 euros per share.
Meanwhile, Italy-based Technoprobe advanced following initiation of analyst coverage by J.P. Morgan. The investment bank assigned an “overweight” rating, signaling confidence in the stock’s future performance.
Spanish property developer Neinor Homes climbed more than 4%. The firm upgraded its financial projections for 2026 and 2027 while unveiling new objectives for 2028 and announcing plans for shareholder distributions.
Bond Yields Take A Breather
Sovereign borrowing costs across the euro area pulled back on Tuesday after reaching levels not seen in decades during the previous week. The differential between French and German 10-year government bonds contracted from last week’s elevated reading.
Market participants had grown increasingly anxious about France’s mounting debt obligations and parliamentary dysfunction. These worries triggered a sharp selloff in French government securities during recent trading.
Rising yields increase financing expenses for corporations and homeowners alike. They simultaneously expand the interest payments governments must service on outstanding obligations.
The euro remained near its lowest level against the U.S. dollar in 17 months. Market commentators cited France’s budgetary difficulties and broader regional political instability as contributing factors to currency weakness.
Analysts at Danske Bank suggested Spain might extend its existing budget framework rather than approve fresh spending measures for 2027. They projected this approach would maintain the country’s debt reduction trajectory while preserving economic momentum in the near term.
Financial markets have also reduced expectations for additional monetary tightening from the European Central Bank. Trading activity now reflects an 80% probability of just one additional rate increase before year-end, down from earlier forecasts of multiple hikes.
ECB Chief Economist Philip Lane indicated in a recent interview that elevated energy costs have not yet triggered significant secondary inflationary pressures. He noted it remained premature to determine whether the bloc faces a worst-case inflation trajectory.
Energy commodity markets experienced some stabilization as well. Crude oil quotations steadied after declining almost 2% in overnight trading, supported by partial normalization of Middle Eastern export activity and G7 commitments to coordinate supply responses if circumstances warrant.
Telecom Plus, which operates the Utility Warehouse brand, advanced 4% after reporting customer acquisition rates exceeding internal projections during the initial half of its fiscal year. Attention now shifts to upcoming euro zone retail sales figures and the commencement of third-quarter corporate earnings reports next week.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


