


Key Highlights
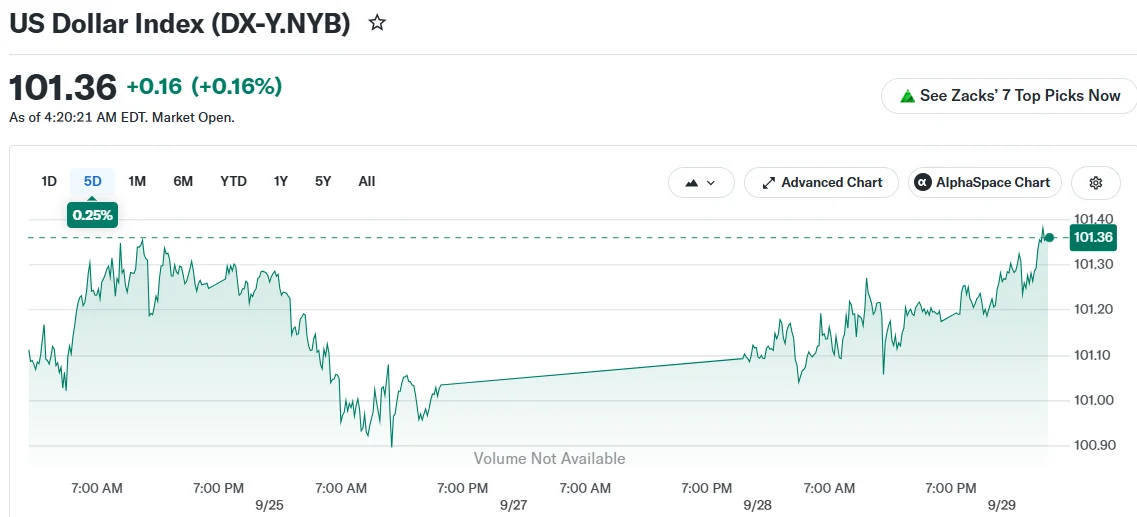
- The greenback index approached a two-month peak on Tuesday, poised for approximately 1.9% monthly gains.
- European and British currencies languished near multi-month lows following dovish ECB commentary on inflation policy.
- Treasury bond yields surged to fresh peaks, with 10-year notes reaching 2007 highs and 30-year bonds touching 2004 levels.
- Australia’s central bank boosted its benchmark rate to 4.60%, marking a 15-year peak and the fourth increase in 2025.
- Market participants await Wednesday’s PCE inflation data and Friday’s employment report for Fed policy direction.
The American currency advanced on Tuesday, maintaining levels near its strongest position in two months. Support came from elevated crude prices and surging government bond yields.
The greenback index, measuring the US currency against major trading partners, registered 101.27. The measure is tracking toward monthly appreciation of roughly 1.8% to 1.9%, representing its strongest performance since June.
Europe’s common currency hovered around $1.1360, approaching its three-month nadir. The weakness followed European Central Bank leadership signaling a measured, gradual strategy for inflation reduction.
Sterling declined 0.1% to $1.3242, positioning it near its own quarterly low versus the American currency.
Crude markets also strengthened. Brent futures advanced beyond $107 per barrel as uncertainty mounted regarding Iranian conflict resolution. President Donald Trump’s rejection of Tehran’s ceasefire offer intensified geopolitical tensions.

Concurrently, a sustained Treasury selloff drove yields to multi-year extremes. The benchmark 10-year note yield advanced to levels unseen since 2007. The 30-year bond yield ascended to its loftiest point since 2004.
The policy-sensitive two-year yield similarly increased, approaching the 5% threshold.
“I think the US dollar is just going to keep growing a little bit higher,” said Joseph Capurso, head of foreign exchange at the Commonwealth Bank of Australia. He added that stronger US economic data could keep pushing interest rates, and the dollar, upward.
Market Pricing Shifts Toward Fed Tightening
Market attention has pivoted to two critical data releases. Wednesday brings the PCE inflation gauge, while Friday delivers the monthly employment situation report.
Both publications are anticipated to strengthen arguments for additional Federal Reserve tightening. Current market pricing suggests over 70% probability of a rate increase by October’s conclusion. This represents a notable jump from the 57% probability estimated just seven days prior.
Asia-Pacific Currency Developments
The Reserve Bank of Australia elevated its policy rate to 4.60% on Tuesday, achieving a 15-year high. The board’s decision was unanimous, representing the fourth tightening action in 2025.
Officials cited persistent inflation pressures, with core inflation measuring 3.6%. Elevated energy expenses and diminished productivity growth were identified as additional concerns.
The Australian dollar momentarily reached $0.7029 following the rate announcement before surrendering those advances. It subsequently declined 0.4% to $0.6989, slipping beneath the psychologically significant $0.70 threshold.
Japan’s currency depreciated to approximately 157.4 against the dollar. This reversed most of Monday’s appreciation, which occurred after Japan’s senior currency diplomat, Atsushi Mimura, issued verbal intervention warnings.
Mimura emphasized that markets should recognize a “very clear” bilateral message from Japanese and American officials concerning yen depreciation. Prime Minister Sanae Takaichi and Finance Minister Satsuki Katayama had delivered comparable statements.
Katayama and US Treasury Secretary Scott Bessent conducted a telephone discussion last Friday. They concurred that the yen’s valuation was excessively weak and committed to enhanced coordination on exchange rate issues.
The New Zealand dollar traded around $0.5675. China’s offshore yuan remained stable at 6.71 per dollar following last week’s bilateral summit, while South Korea’s won and Singapore’s dollar registered minimal fluctuations.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


