


TLDR
- Precious metals experienced significant losses Monday, with gold declining 3% to reach $4,156.45 per ounce, a seven-week bottom.
- Escalating oil prices linked to tensions between Iran and the US over the Strait of Hormuz are intensifying inflation concerns.
- Market participants now estimate a 70.3% probability of another Federal Reserve rate increase in October.
- Silver plummeted nearly 5%, with platinum and palladium posting similar losses.
- Investors await key economic indicators this week, including PCE inflation figures and September employment data.
Gold prices experienced a substantial decline Monday, tumbling 3% to reach their weakest position in over seven weeks. Spot gold settled at $4,156.45 per ounce, while December-delivery US gold futures decreased 3.1% to $4,188.80.
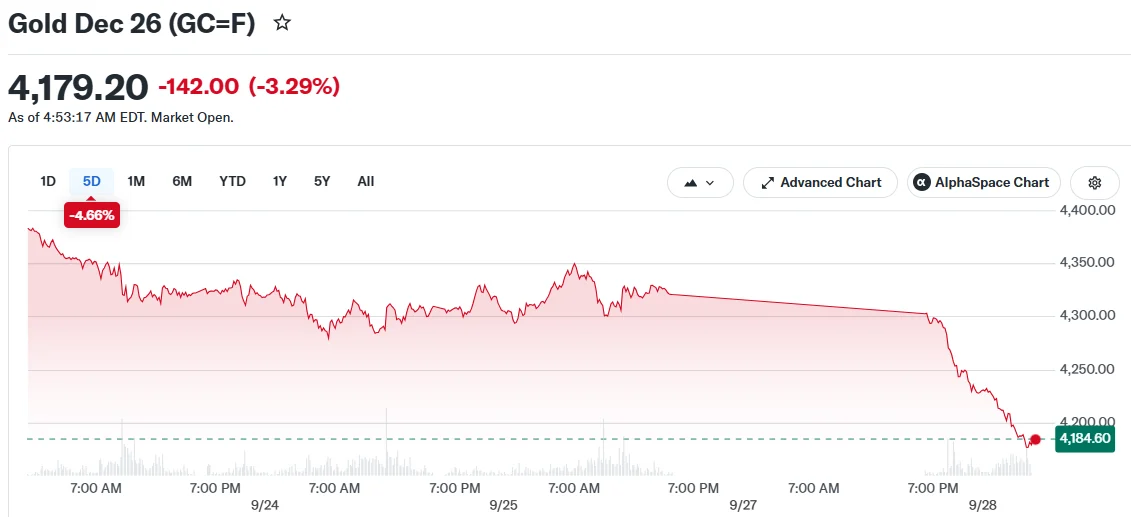
The downturn follows a previous week where gold shed over 2%. Elevated crude oil prices combined with mounting expectations for additional Federal Reserve monetary tightening are the primary catalysts behind the precious metal’s weakness.
Crude Prices Surge Amid Iranian Standoff
Brent crude experienced a rebound following President Donald Trump’s rejection of a diplomatic proposal from Iran. The agreement would have addressed the current crisis and restored access to the Strait of Hormuz, a critical artery for international oil transportation.
Iranian officials indicated they would maintain their position regarding the reopening of the strategic waterway. While Trump expressed optimism about resuming negotiations with Tehran this week, the impasse persists.
The confrontation between the United States and Iran has entered its eighth month. Year-to-date, Brent crude has surged approximately 70%.

Elevated energy prices typically amplify inflationary pressures as they cascade through various sectors of the economy. This dynamic is reinforcing expectations that the Fed will maintain restrictive monetary policy.
Federal Reserve Tightening Expectations Intensify
Market participants now assign a 70.3% probability to another Federal Reserve rate increase in October, based on CME’s FedWatch Tool data. The central bank implemented a quarter-point rate elevation earlier this month.
Multiple Fed policymakers have signaled openness to additional tightening measures. Cleveland Fed President Beth Hammack expressed concern that prolonged elevated inflation might condition consumers to accept higher prices as the new baseline. She emphasized the central bank’s commitment to preventing such an outcome.
Hammack further noted that long-dated Treasury yields are experiencing upward pressure from enhanced growth projections, fiscal sustainability concerns, and anticipation of continued rate increases.
Elevated borrowing costs diminish gold’s appeal among investors. Since the precious metal generates no income stream, rising yields on bonds and deposit accounts often prompt capital reallocation away from bullion.
The US dollar maintained strength Monday, simultaneously making gold costlier for international purchasers. US Treasury yields continued their upward trajectory as well.
Additional precious metals mirrored gold’s decline. Spot silver plunged 4.8% to $61.17 per ounce. Platinum retreated 2.4% to $1,735.88, while palladium shed 2.2% to settle at $1,239.60.
Notwithstanding the recent selloff, gold remains substantially below its January record near $5,600. Throughout this month, the metal has largely traded within a $4,230 to $4,510 corridor.
Gold exchange-traded fund appetite has remained robust. ETF holdings have expanded by approximately 50 tonnes this month despite price declines.
US consumer confidence deteriorated in September, reaching a four-month nadir. Heightened anxieties regarding inflation and overall economic conditions drove the decline.
Treasury Secretary Scott Bessent advocated for Federal Reserve flexibility on monetary policy. He suggested that productivity improvements, partially attributable to artificial intelligence adoption and regulatory reform, could help contain inflationary pressures.
Market attention now shifts to this week’s economic releases. Wednesday features the August PCE inflation report, the Fed’s preferred price gauge. Friday’s September employment data will provide additional insight into labor market dynamics.
These indicators are anticipated to significantly influence market expectations regarding the Federal Reserve’s subsequent policy decision.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


