Key Takeaways
- The fast-food giant introduced its NEXT growth initiative at Investor Day, featuring store renovations and artificial intelligence integration.
- McDonald’s announced approximately $8.5 billion in franchisee assistance extending to 2036, with $5 billion allocated by 2030.
- Shares dropped 5% following the announcement and reached a nearly four-year bottom at $234.03.
- Domestic same-store sales declined in July and August, with third-quarter results anticipated to be marginally negative.
- Multiple Wall Street firms reduced their price projections, though several maintained optimistic outlooks for the long haul.
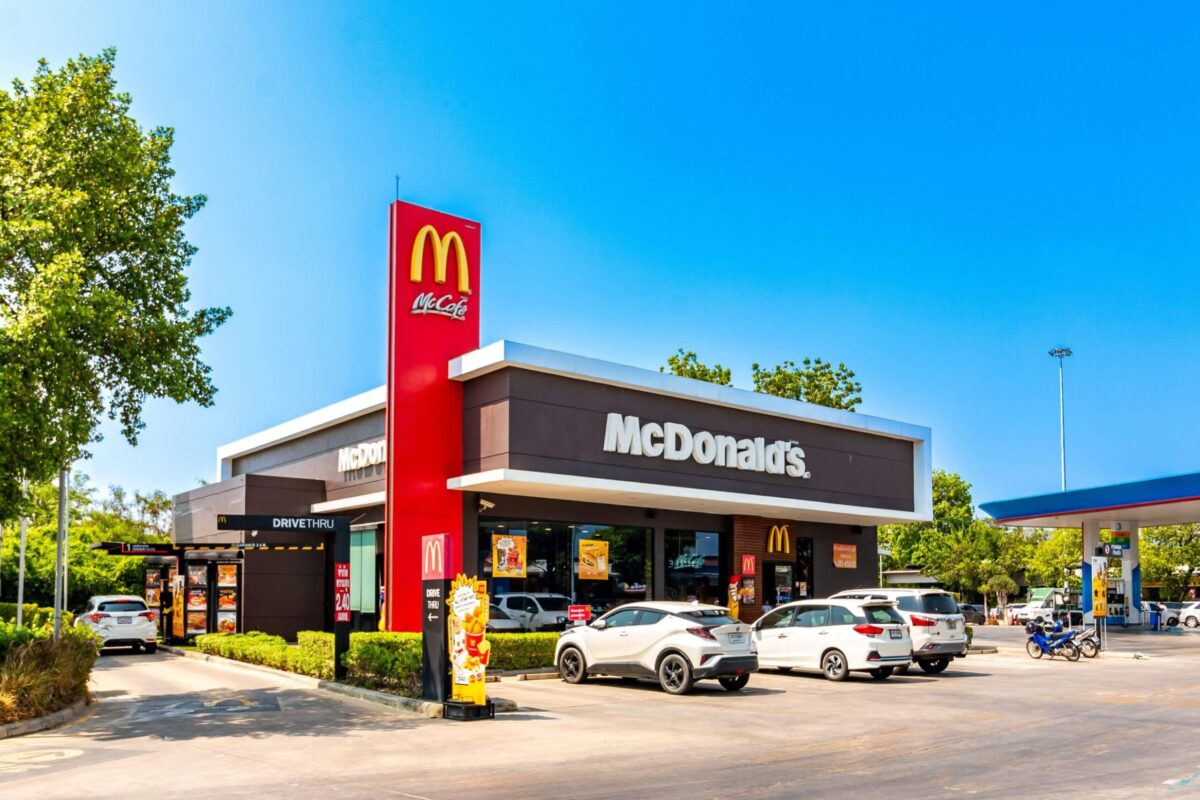
Shares of McDonald’s have tumbled to their lowest point in nearly four years as Wall Street digested the company’s ambitious expansion strategy. The stock plunged almost 5% last Wednesday and experienced an intraday decline of up to 6.5% before recovering slightly. Trading pressure continued Thursday and Friday, pushing the year-to-date loss to approximately 23%.
The sharp decline came after McDonald’s Investor Day presentation, during which executives outlined the NEXT initiative. This comprehensive strategy encompasses store modernization, menu innovation, precision marketing, and artificial intelligence integration for ordering and supply chain management.
While the strategic vision appears sound, market participants are primarily concerned about implementation costs and the extended timeframe required to realize returns.
Understanding the Market Reaction
McDonald’s committed to investing approximately $8.5 billion in franchisee assistance through 2036. The initial phase allocates around $5 billion before 2030, including rent concessions and $1.5 billion to $2 billion in capital assistance.

Company leadership projects these investments will enhance restaurant-level profitability by 2.5 percentage points. This translates to approximately $100,000 in incremental annual cash generation per typical U.S. outlet.
The ultimate goal: achieving an adjusted operating margin in the low-to-mid-50% range by decade’s end. That represents a significant jump from 47% recorded in the first half of 2026. However, reaching this target demands substantial upfront capital, creating anxiety among shareholders focused on immediate performance.
Bernstein analyst Danilo Gargiulo identified the spending commitment as the event’s “biggest surprise.” His analysis suggests complete implementation could require roughly $800,000 per average domestic restaurant, layered on top of standard renovation expenses.
Bank of America analysts calculate that restaurants need to generate 7% to 8% revenue growth to validate the investment, based on a 70/30 cost-sharing arrangement between franchisees and corporate. Given current operating conditions, this represents a challenging hurdle.
Weakening Sales Momentum
Customer traffic patterns compound the challenge. McDonald’s disclosed that domestic same-store sales declined in both July and August, with third-quarter results expected to finish marginally negative despite September showing modest recovery.
Second-quarter global comparable sales advanced just 1.3% year-over-year. This marks a deceleration from 3.8% growth in the opening quarter and 3.1% for the full 2025 period. Domestic customer visits actually contracted.
Raymond James analyst Brian Vaccaro emphasized that NEXT’s effectiveness will require measurement “in years rather than quarters.” The company hasn’t provided detailed rollout schedules for multiple program components, creating uncertainty around execution timing.
Vaccaro highlighted value perception challenges. With many quick-service meals now priced between $10 and $13, McDonald’s faces intensified competition from casual dining chains and fast-casual concepts offering competitive deals.
Multiple investment banks adjusted their outlooks following the presentation. Baird reduced its target to $250 while maintaining a Neutral stance. BTIG lowered expectations to $295 but preserved its Buy recommendation. RBC moved to $285 with a Sector Perform designation. JPMorgan decreased to $260 while retaining an Overweight rating.
However, not all analysts adopted a defensive posture. UBS reaffirmed its Buy rating and $320 price objective, highlighting the NEXT strategy’s emphasis on same-store sales expansion and customer traffic growth.
J.P. Morgan’s John Ivankoe suggested McDonald’s data capabilities could provide competitive advantages versus smaller competitors. Deutsche Bank’s Lauren Silberman expressed increased conviction that AI applications can enhance unit-level profitability over the medium term.
BMO’s Andrew Strelzik considers the margin objectives attainable and remains constructive on valuation. Nevertheless, he anticipates limited near-term appreciation until capital deployment translates into measurable growth acceleration.
Over half of analysts monitored by FactSet continue to rate MCD as a Buy. The consensus price target implies approximately 27% upside from current trading levels.
Bernstein maintained its Market Perform designation and $295 valuation, observing that the beverage initiative hasn’t generated sufficient sales momentum to counterbalance broader headwinds. The firm also noted that the chicken platform launch timeline extends beyond initial expectations.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants