


Key Highlights
- Major U.S. stock indices declined Thursday, erasing early session advances.
- The 10-year Treasury yield climbed to approximately 5.3%, marking a fresh multidecade peak.
- Micron Technology surpassed earnings forecasts and upgraded guidance, yet shares remained flat.
- Manufacturing data revealed weaker-than-anticipated expansion alongside climbing input costs.
- Weekly unemployment claims decreased for the fourth consecutive week, signaling labor market resilience.
U.S. Stocks retreated Thursday as surging Treasury yields dominated investor sentiment, eclipsing an impressive quarterly report from Micron Technology. The downturn marked the opening session of October trading.
The Dow Jones Industrial Average declined approximately 0.5%. Meanwhile, the S&P 500 lost 0.3%, with the Nasdaq Composite similarly sliding around 0.3%.
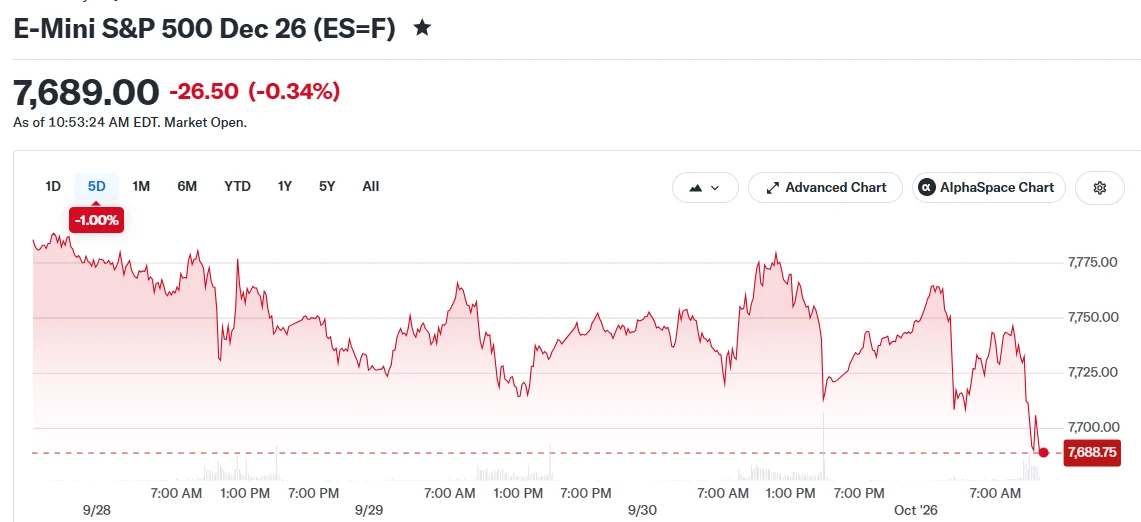
Each benchmark index had traded in positive territory during early hours. However, momentum reversed as mounting bond market concerns intensified throughout the trading session.
Treasury Yields Continue Upward March
The benchmark 10-year Treasury yield advanced again Thursday, climbing to roughly 5.3%. This level represents a fresh multidecade peak for the critical rate.
The increase follows a brutal quarter for fixed-income securities. Bond markets had just endured their weakest quarterly showing in decades as October commenced.

Elevated yields increase borrowing costs across the economy. They simultaneously diminish equities’ relative appeal, as investors can secure higher returns from lower-risk government securities.
Rate-sensitive market sectors bore the brunt of Thursday’s selling. Materials, real estate, and financial shares ranked among the session’s worst performers.
Energy and technology were the sole sectors maintaining positive ground. At one point during morning trading, fewer than one-third of S&P 500 constituents showed gains.
Manufacturing Reports Disappoint
Thursday brought two distinct manufacturing activity reports. Each indicated expansion rates falling short of forecasts.
The S&P 500’s Manufacturing Purchasing Managers Index registered 55.9 for September. This reading trailed the preliminary estimate of 57.
Meanwhile, the Institute for Supply Management reported manufacturing input prices accelerated sharply during September. Escalating production costs can compress corporate margins while stoking inflationary pressures.
These releases followed a challenging conclusion to the third quarter. The Dow recorded declines for both September individually and the complete quarter, though the Nasdaq managed quarterly gains.
Micron Technology delivered fourth-quarter results exceeding Wall Street projections. The memory semiconductor manufacturer also elevated its first-quarter forecast.
Notwithstanding the robust performance, Micron shares traded essentially unchanged. Market participants appeared fixated on fixed-income dynamics rather than individual corporate achievements.
Other semiconductor and technology stocks posted varied outcomes. One leading chipmaker edged higher following a strong September performance, while another semiconductor name retreated after surging 30% the previous month.
Employment data suggested continued stability. Initial unemployment claims dropped for a fourth consecutive week according to the latest figures.
A complementary report from Challenger, Gray & Christmas examining planned workforce reductions showed companies announced fewer September job cuts. Simultaneously, organizations have refrained from aggressive hiring campaigns.
These employment indicators arrive ahead of Friday’s highly anticipated monthly jobs report. That comprehensive release will provide deeper insight into hiring momentum and unemployment dynamics.
Nike’s quarterly earnings announcement is scheduled for Thursday’s after-market close. The athletic apparel giant’s shares have traded near their lowest valuation since 2014, prompting investors to scrutinize results for recovery signals.
As late-morning trading continued, the 10-year yield stood at 5.33%, while the 2-year yield retreated to 4.852%. The Dow traded down approximately 328 points, with the S&P 500 declining 0.36% and the Nasdaq falling 0.31%.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


