


Key Takeaways
- UBS reduced its KOSPI 12-month forecast to 8,000 from 8,800, representing a reduction of almost 10%
- Rising interest rates, an appreciating Korean won, and crude oil trading above $100 per barrel are primary headwinds
- September marked the first negative month-over-month earnings-per-share revision consensus this year, falling 0.7%
- The bank maintains expectations for robust KOSPI earnings expansion of 256% in 2026 and 38% in 2027
- Samsung Electronics and SK Hynix shares advanced following gains in a major US semiconductor index
Investment bank UBS has reduced its 12-month forecast for South Korea’s KOSPI index to 8,000 from its previous 8,800 target. The substantial revision, representing a decline of approximately 10%, comes as the market faces intensifying challenges from monetary tightening, currency appreciation, and elevated energy costs.
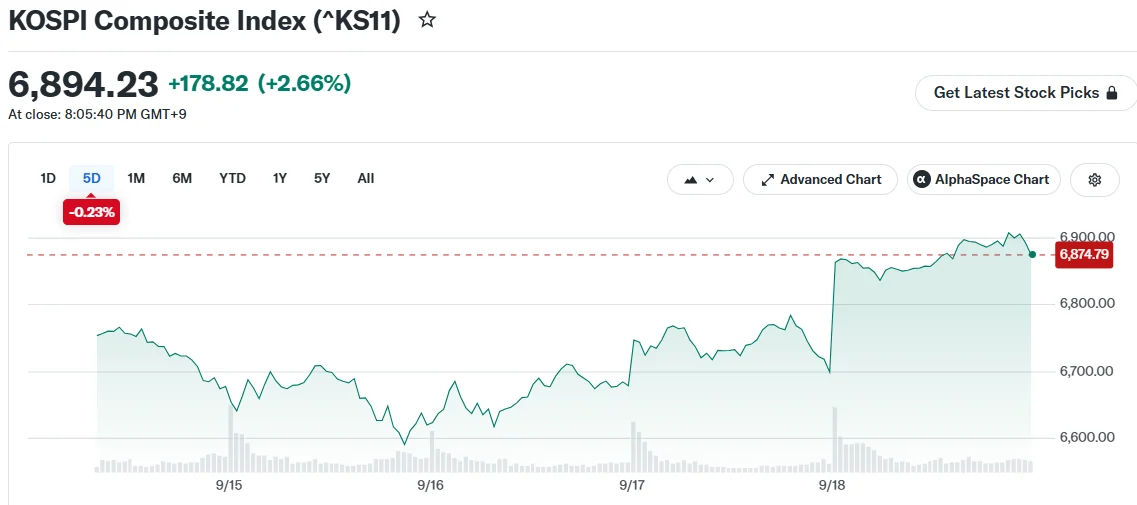
In a research note released Friday, analyst Yong-Suk Son outlined the rationale behind the downgrade. The firm adjusted its implied earnings multiple downward to 7 times from 8 times, acknowledging the intensifying macroeconomic challenges despite projections for continued earnings expansion.
A notable development is that consensus earnings-per-share estimates recorded their first negative monthly revision in September, declining 0.7% compared to August. This marks a reversal from the positive momentum seen throughout the earlier months of the year, particularly as the memory chip sector upgrades that previously supported market gains have now shifted direction.
Nevertheless, UBS maintains its forecast for substantial KOSPI earnings-per-share expansion of 256% in 2026 and 38% in 2027. According to Son, the index is likely to trade within a limited range until third and fourth quarter earnings reports provide additional insight into whether these growth projections remain achievable.
Monetary Tightening and Energy Costs Drive Bond Yields Up
South Korea’s central bank has implemented two interest rate increases since July. The benchmark 10-year government bond yield has surged to 4.5% from 3.4% at the beginning of the year. Meanwhile, crude oil trading above $100 per barrel continues to fuel inflationary concerns.

Currency appreciation presents an additional challenge for Korean exporters. According to UBS analysis, each 1% strengthening of the won against foreign currencies results in approximately 1.1% decline in KOSPI earnings.
The investment bank established an optimistic KOSPI scenario at 9,200 and a pessimistic scenario at 5,100, creating a substantial range that underscores the current market uncertainty.
From a sector perspective, UBS continues to favor memory chip manufacturers. The firm highlights Samsung Electronics and SK Hynix among its preferred holdings. Nevertheless, the bank is gradually rotating toward value-oriented and quality companies that provide shareholder distributions, considering the decelerating market momentum and more restrictive liquidity conditions.
Regional Equity Markets and Semiconductor Stocks Advance
In separate market action, Asian equities and fixed income securities posted modest gains Friday as energy prices moderated. Brent crude decreased 0.8% to approximately $104 per barrel, providing some relief from inflation worries.
Shares of Samsung Electronics and SK Hynix both moved higher following strength in a prominent US semiconductor benchmark. US equity markets had recorded their strongest performance since August in the previous trading session, recovering from declines that followed the Federal Reserve’s initial rate increase since 2023.
The 10-year US Treasury yield declined nine basis points to 4.93% as crude oil prices retreated. Earlier in the week, yields had reached 5.02% following the Fed’s policy decision.
MSCI’s Asia-Pacific equity benchmark gained 0.5%, although declining stocks outnumbered advancing ones, indicating the rally lacked broad market participation.
The pullback in energy costs may provide central banks with additional flexibility to evaluate the effects of restrictive monetary policy, potentially offering near-term support for both equity and bond markets.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


